If your family has ₹75 lakh to put to work, you are probably weighing a second home vs a mutual fund or a simple bank fixed deposit. Here is the honest 10 year arithmetic in rupees, including tax, risk and what you can actually do with each one on a Friday evening.
What ₹75 lakh in a bank fixed deposit gives you
Suppose you have ₹75 lakh ready, or you are ready to commit ₹50,000 a month over the next decade. Every builder brochure will tell you property is the best place for it. We build second homes between Mumbai and Nashik, and we are going to tell you something different. On pure paper numbers, financial assets often win.
Let us start with the safest choice. Assume you put ₹75 lakh into a bank fixed deposit at an assumed rate of 6.5% a year, paying out monthly so you can compare it with rent. Notice that 6.5% on ₹75 lakh is ₹4,87,500 a year, or about ₹40,625 every month. Over 10 years, that adds up to ₹48,75,000 in total interest before tax.
The catch is how the taxman treats it. Fixed deposit interest is added straight to your salary or business income. For a family in the 30% tax bracket, about ₹1,46,250 a year goes to tax. Your ₹4,87,500 a year becomes roughly ₹3,41,250 in hand, or about ₹28,400 a month. At the end of year 10, you have collected about ₹34.12 lakh after tax, and the bank gives you back your original ₹75 lakh.
What ₹75 lakh in an equity mutual fund could grow into
Now look at the second home vs mutual fund question. Equity mutual funds do not pay a fixed monthly cheque. You buy them for long term growth, and the value goes up and down with the stock market. Any number here is an assumption, not a promise.
If an equity mutual fund grows at an assumed 10% a year for 10 years, ₹75 lakh becomes about ₹1.94 Cr. That is a gain of ₹1.19 Cr on paper. If it grows at an assumed 12% a year, ₹75 lakh becomes about ₹2.33 Cr, which is a gain of ₹1.58 Cr. When you sell after 10 years, you pay long term capital gains tax on the profit, which is still far gentler than the annual tax on a fixed deposit.
If your only goal is to turn ₹75 lakh into the largest possible pile of money in 10 years, and you will not panic when the market drops by 20% in a bad year, the mutual fund wins this comparison. No honest developer should tell you otherwise.
What a ₹75 lakh Glass Resort Suite actually pays you
So why do Mumbai families still look at property? Let us put a real project on the table. Our Glass Resort Suites at the Blue Lagoon resort, registered under MahaRERA PR1330002500101, are priced at ₹75 lakh all inclusive. You can also pay through a developer payment plan of ₹50,000 a month for 120 months with ₹1 lakh to reserve, 10% within 15 to 20 days, and another 10% in the 18th month, with no bank and no interest.
The suite comes with an assured monthly rent written into the registered agreement for 15 years, starting from the 19th month. In year 1 of the rental term, it pays ₹21,000 a month, which is ₹2,52,000 for the year. That is about 3.4% on ₹75 lakh before tax. The rent steps up by ₹1,000 a month every year, reaching ₹30,000 a month in year 10 and ₹35,000 a month in year 15, which is ₹4,20,000 a year or about 5.6% on ₹75 lakh.
Across the first 10 years of rent payouts, from ₹21,000 rising to ₹30,000 a month, you collect ₹30,60,000 in gross rent. Across the full 15 year rental term, the total rent paid out is ₹50,40,000. Maintenance charges are zero for all 15 years because Pool City runs the resort and handles upkeep and housekeeping.
Rental income also gets a standard 30% deduction under income tax law before your slab rate applies. That means if you collect ₹3,00,000 in rent in a year, ₹90,000 is automatically tax free for upkeep, even though you paid nothing for maintenance. Only the remaining ₹2,10,000 is taxed. At the 30% slab, you pay about ₹63,000 in tax and keep ₹2,37,000.
Why you cannot spend a weekend inside a mutual fund
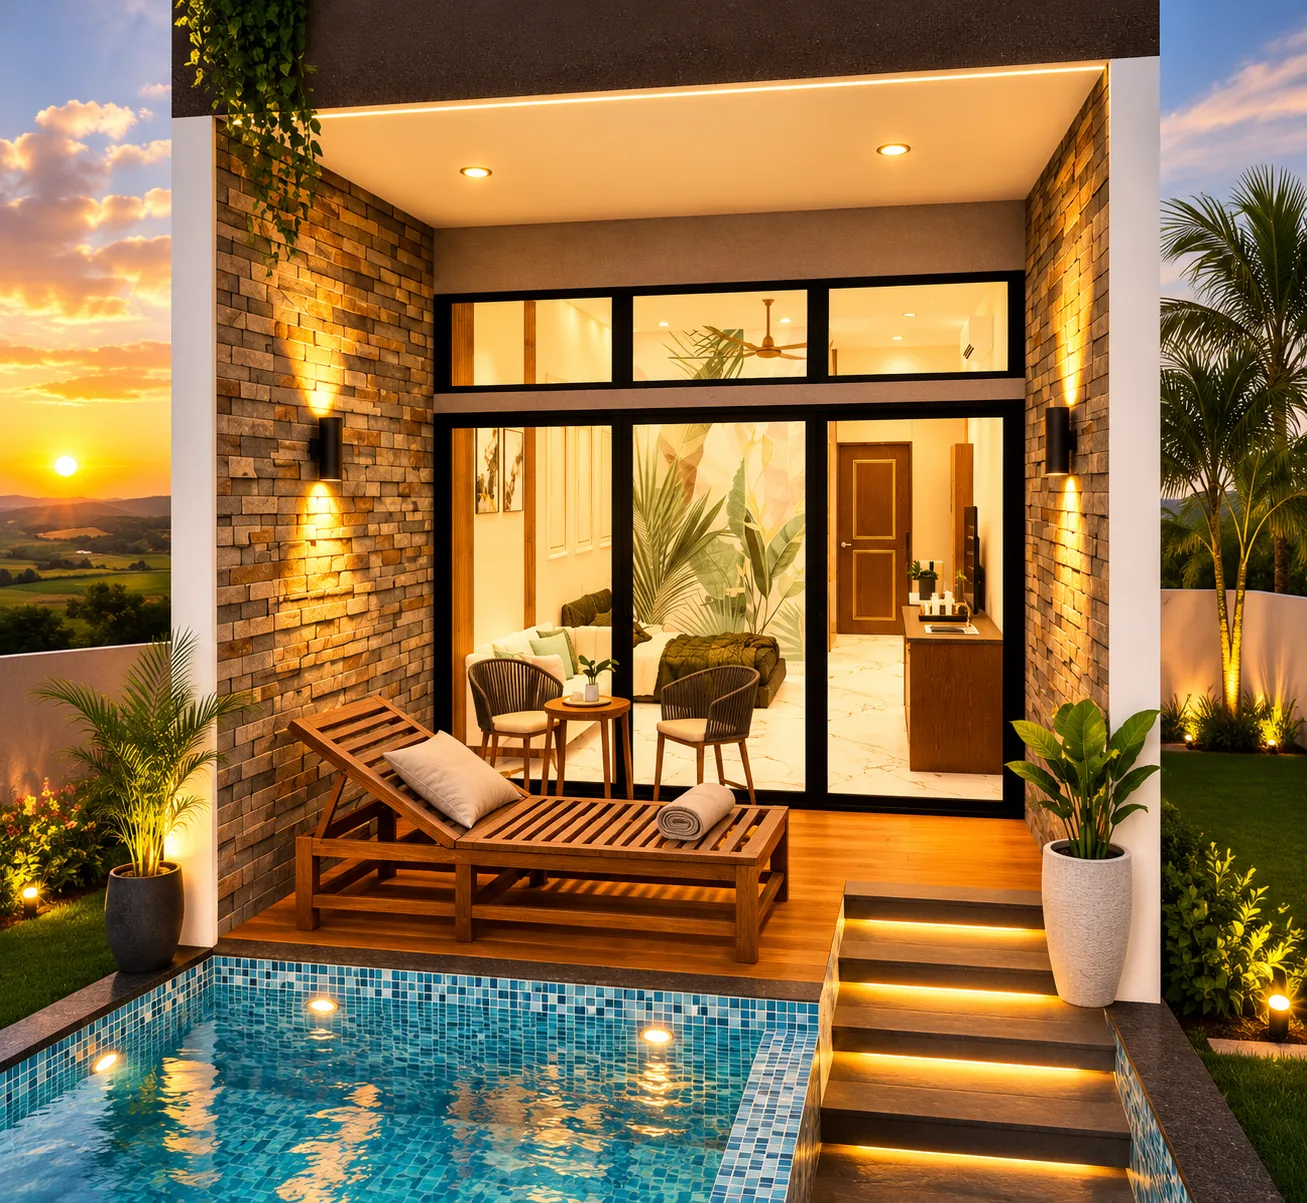
When you compare a second home vs a mutual fund, the spreadsheet leaves out what happens on Saturday morning. A mutual fund statement sits on your phone. A resort suite is about 90 minutes from Mumbai on the Mumbai to Nashik highway, with two en suite bedrooms, floor to ceiling glass walls, a glass ceiling for stargazing, a private rooftop lounge and a 16,000 sq ft lagoon outside your door.
With the Glass Resort Suites, you also get 21 complimentary holiday nights every year. That includes 14 nights at the resort and a 7 night international holiday. If your family normally spends ₹10,000 to ₹15,000 a night on two rooms at a good resort near Mumbai, using those 14 nights saves you ₹1.4 lakh to ₹2.1 lakh every year in hotel bills you would have spent anyway.
At the end of 10 or 15 years, a fixed deposit gives back the exact ₹75 lakh you put in, which buys much less than it did a decade ago. With the suite, you still own a registered property in your name. We never promise or predict a number for property price growth, because nobody knows the market 10 years out. What we can say is that the suite remains yours, registered in your name.
The real risks and how fast you can get your money out
Every option has a flaw, and you should know which flaw you are signing up for before you write a cheque. None of the three is perfect.
- Liquidity: A fixed deposit can be broken in a day with a small penalty. A mutual fund comes back to your bank account in two or three working days. A second home takes months to sell, because you have to find a buyer and register a sale deed.
- Income risk: Fixed deposit interest is backed by a bank. Mutual fund returns are not fixed at all and can be negative in bad years. Assured rent on a resort suite is a legal promise in a registered agreement, paid whether your suite is booked or empty, but it still depends on the developer running the resort well.
- Effort: Neither a fixed deposit nor a mutual fund ever calls you about a leaking tap. A standalone farmhouse will. That is why we only offer assured rent on properties we manage ourselves, like the Glass Resort Suites and our Kasara pool villas where rent goes up to ₹40,000 a month on a ₹1.09 Cr starting price.
How to decide which bucket your ₹75 lakh belongs in
Do not put your emergency money or your child's college fund into a weekend home. If you might need the ₹75 lakh back at short notice in three years, keep it in a fixed deposit or a liquid fund. If your goal is pure compounding over a decade and you already holiday where you like, a mutual fund is built for that job.
Look at a second home vs a mutual fund only when two things are true at once. First, your core retirement and emergency investments are already running. Second, you want part of your money to buy something your family can drive to on a Friday evening, while still sending a predictable cheque to your bank account every month.
Before you decide, sit down with your chartered accountant or a SEBI registered financial adviser and run these exact numbers against your tax slab. If you want to see how our side of the math works on paper, ask our team for the draft agreement and the 15 year rental schedule for the Glass Resort Suites, and have your lawyer read every page.
Read next
- What a ₹75 Lakh Holiday Home Actually Earns in Ten Years
- Real Estate vs Gold: Which One Actually Pays You Back?
- Tax on a Second Home in India — What You Actually Pay
- See all Pool City projects, with prices and locations
*T&C apply. MahaRERA PR1330002500101 for Glass Resort Suites. Registration details for other projects are shared on request. Fixed deposit and mutual fund figures are illustrative assumptions, not promises or financial advice. Tax rules are general guidance; please consult a qualified tax or financial adviser. Rental income and payment plans are as per the registered agreement.
Want to see the 15 year rental schedule in writing?
Ask us for the Glass Resort Suites agreement summary and check the numbers with your own adviser.
WhatsApp usCall +91 70426 33644Other ways to reach us